While some economies in the region benefit from sound macroeconomic fundamentals, Romania remains exposed to significant vulnerabilities, particularly in the area of public finances and external imbalances. Domestic economic recovery is sluggish and risks associated with the fiscal and external position have increased considerably, putting Romania at a negative relative position vis-à-vis other economies in the region.
At the same time, overall global country risk has improved in 2025, with 36 ratings positively revised and only 14 downgraded, according to the latest Allianz Trade analysis. The development reflects the ability of several economies to adjust their fiscal, monetary and trade policies in a difficult international environment. Among the countries showing improvements are Argentina, Ecuador, Ecuador, Hungary, Italy, Spain, Turkey and Vietnam. In Central and Eastern Europe, the trend is mixed.
Inflation continues to set Romania apart from the rest of the region
Although inflation is on a downward trend at the regional level, Romania continues to have one of the highest inflation rates in Central and Eastern Europe. Price pressures are fueled by structural rigidities, wage dynamics and incomplete monetary policy transmission. This affects the purchasing power of the population and maintains a high degree of uncertainty for the business environment. Compared to other economies in the region, the more rapid moderation in inflation has allowed a clearer normalization of economic conditions.
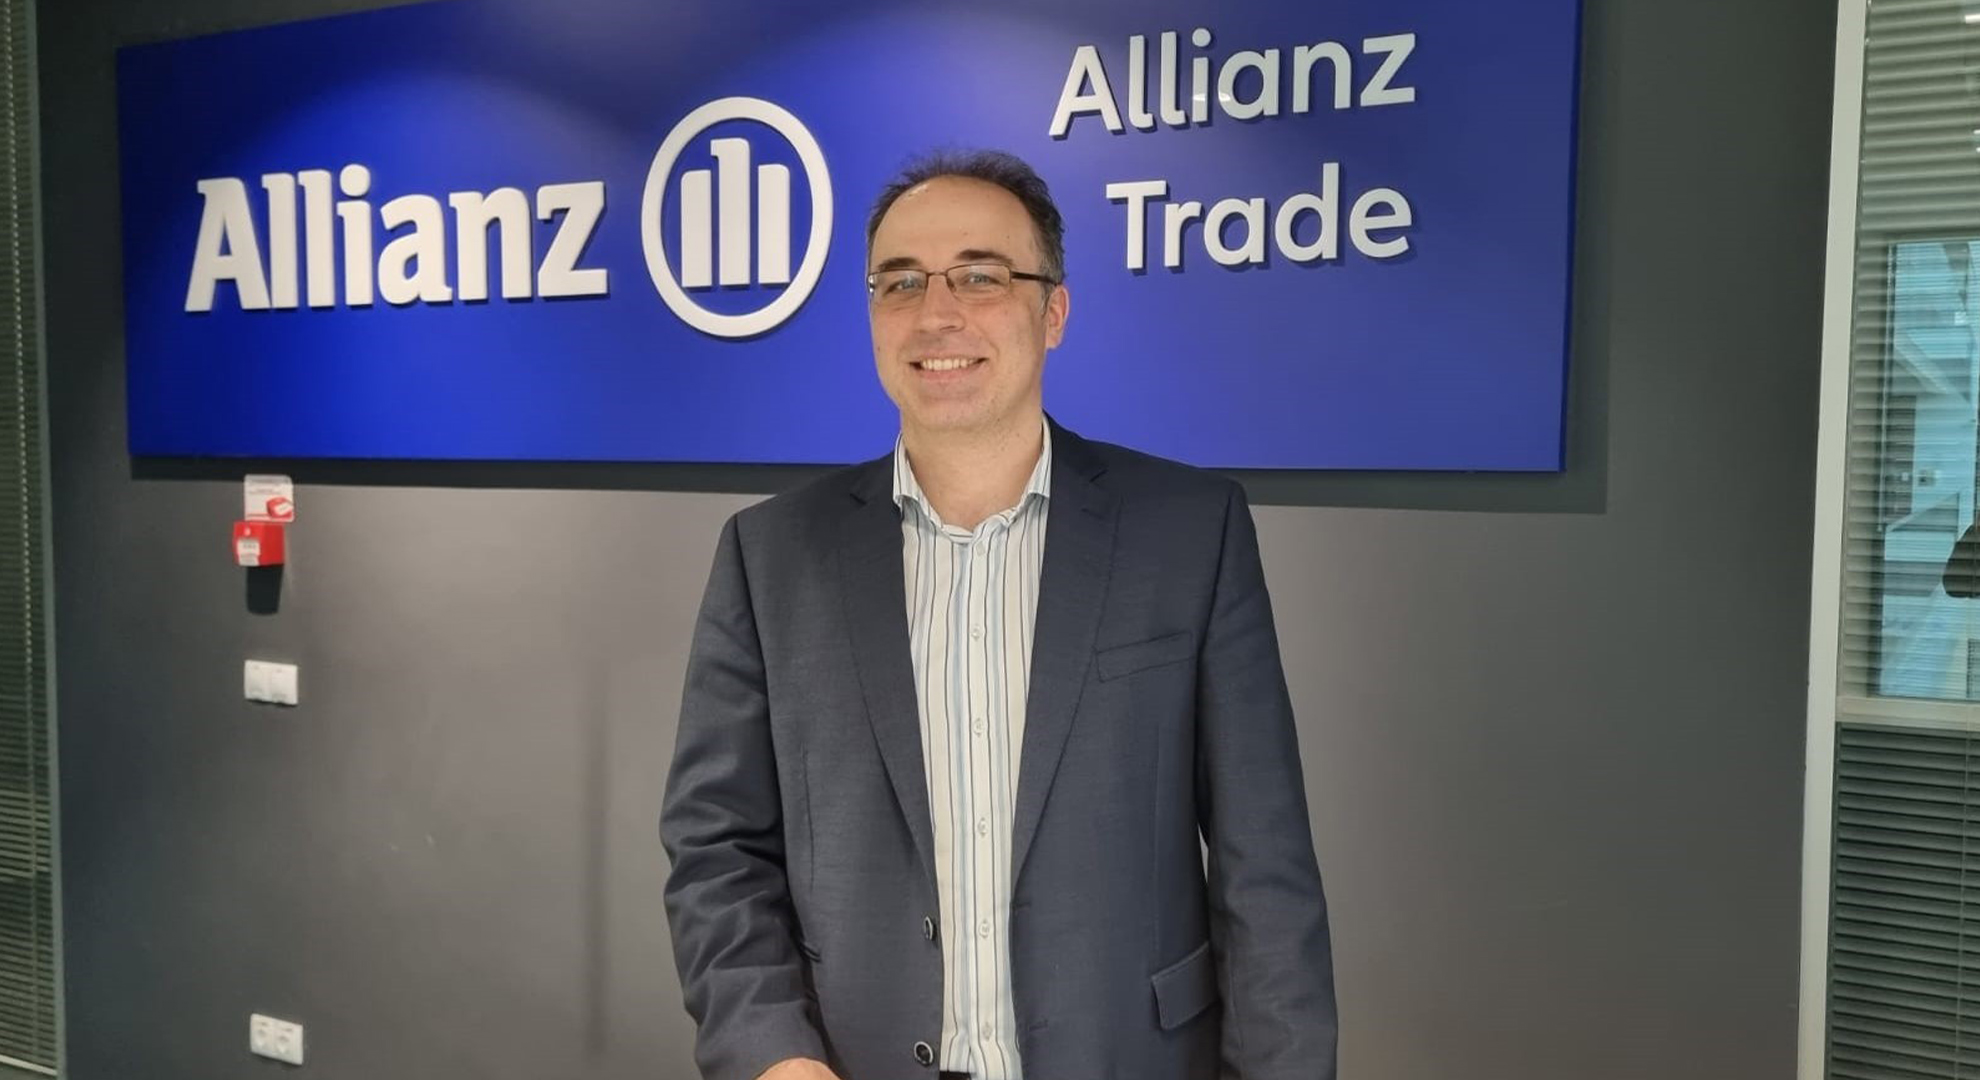
„There is, however, some good news about the reduction in the budget deficit for the end of 2025, which should continue in the coming years. Indeed, political uncertainties persist and risk derailing the government's commitments to reduce the deficit also through the leverage of reducing government spending (after the first revenue-raising lever, through taxes, has already been used). However, one cannot help but notice that the imminent risk of a downgrade has been overcome in the short term and Romania is borrowing at lower costs compared to the first half of 2025. At the micro level, assailed by the spectre of inflation and payment delays, companies are showing increased caution at the beginning of the year in terms of future plans, with an effect on investment and private consumption. Against this backdrop, there is a growing likelihood that from the second half of the year, if not earlier, the discussion on the direction of the economy will shift from inflation (which will not go away) to ways to boost growth, consumer sentiment and possibly lower bank interest rates”says Mihai Chipirliu, Credit Director, Allianz Trade Romania.
Slow economic recovery in a more favorable regional context
After a modest economic performance, Romania's economy continues to recover at a slower pace than most Central and Eastern European economies. Although the regional business cycle is beginning to stabilize, Romania remains hampered by persistent domestic imbalances, which are holding back the recovery in demand and investment. Compared to other economies, Poland or the Czech Republic benefit from stronger macroeconomic fundamentals, which allow them to normalize economic activity more rapidly.
However, Romania's most important vulnerability remains the sharp deterioration in its fiscal and external position. The budget deficit has widened to 8.7% of GDP in 2024, on the back of significant increases in public sector pensions and wages, as well as high spending associated with the electoral cycle. At the same time, the current account deficit widened to 8.2% of GDP, reflecting rising imports, weak export performance and loss of cost competitiveness. All these factors have led to an external position assessed as significantly weaker than the level consistent with the economic fundamentals and policies deemed sustainable. Although Romania maintains its investment grade status, all major rating agencies have revised the outlook to negative, raising concerns about fiscal sustainability and financing vulnerabilities.
External financing riskier than in other CEE countries
The current account deficit is increasingly being financed by debt generating flows. Portfolio investment accounts for more than two-thirds of external financing, which increases the exposure of the Romanian economy to sudden shifts in investor sentiment and financial market volatility.
To reduce fiscal and external imbalances, the authorities have adopted a package of fiscal measures, including tax hikes and expenditure restraint measures. However, financing risks remain high in the context of still high deficits and rising public debt. In addition, absorption of EU funds remains sluggish. By mid-2025, the NGEU utilization rate was about 38% and the Structural Funds about 17% of committed amounts, lower levels than in other countries in the region. Low administrative capacity and bottlenecks in public procurement procedures continue to hamper investment implementation. Although the business environment is considered adequate, the lack of structural reforms in key economic sectors and slow execution of public investment limit medium-term growth potential. These constraints affect the competitiveness and ability of the economy to catch up with other Central and Eastern European economies.
„In 2025, the improvements were mainly driven by stronger macroeconomic fundamentals supported by more favorable fiscal and monetary policies. In many emerging markets, better financing conditions, appreciating local currencies and higher commodity prices have allowed the removal of transaction restrictions. Among high-income economies, improved political stability, disinflation and stronger trade performance have strengthened resilience in Europe (especially in Germany, Greece, Italy and Spain) and the Asia-Pacific region (including South Korea and Vietnam)”says Ana Boata, Head of Economic Research, Allianz Trade.
Political instability has complicated macroeconomic adjustment
Government instability and political fragmentation affect the consistency and predictability of economic policies. Recent electoral pressures have contributed to a loosening of fiscal discipline, amplifying macroeconomic imbalances in an uncertain regional and global context.
In conclusion, Romania is not facing an imminent crisis, but it remains one of the most exposed economies in Central and Eastern Europe, both because of persistent inflation, high deficits and rising financing risks, as well as structural constraints that limit adjustment capacity.